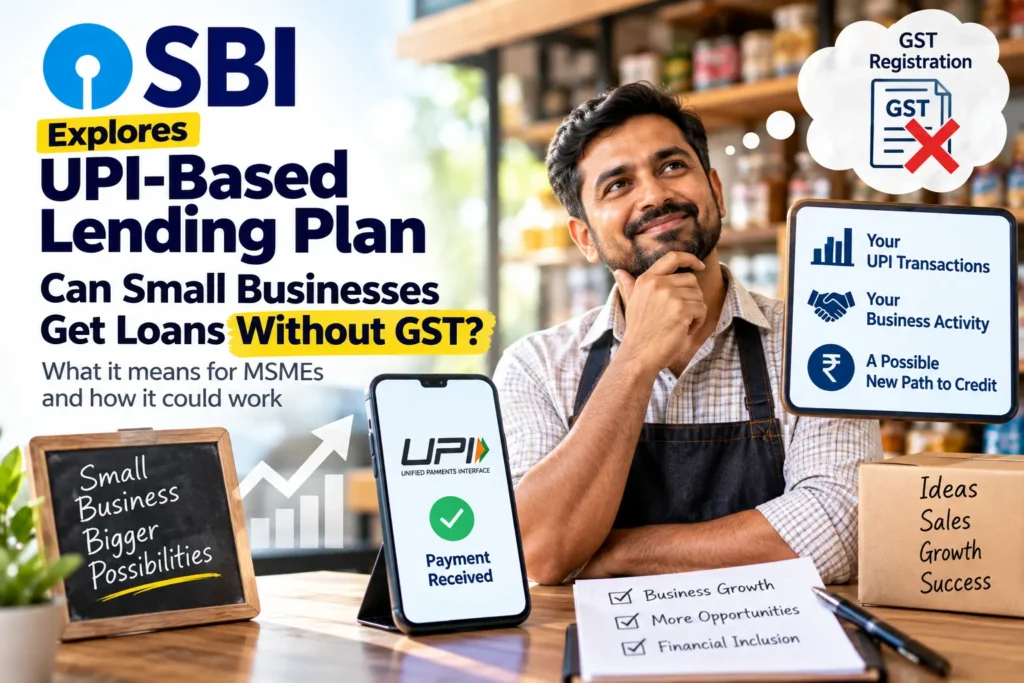
Small businesses that do not have GST registration could soon find it easier to access formal business credit.
State Bank of India (SBI) is developing a new lending solution that could use UPI transaction data to assess the creditworthiness of small businesses that do not have GST registration. SBI Managing Director Ashwini Kumar Tewari disclosed the plan at the Global Fintech Fest in Mumbai.
How could an SBI UPI business loan without GST could work?
Traditionally, GST data can give lenders a useful picture of a business’s reported sales and cash flow.
For businesses outside the GST system, however, that data may not be available.
SBI is exploring whether regular UPI transaction history can act as a proxy for sales. With the customer’s consent, the bank could potentially combine UPI payment information with other data to assess repayment capacity.
In simple terms:
Regular digital sales → visible UPI cash flow → better business profile → potential access to formal credit.
Who could benefit?
The proposed approach could be particularly useful for micro businesses, small shops, traders, service providers and other eligible businesses that receive a significant portion of their customer payments digitally.
For such businesses, a consistent UPI payment trail could demonstrate that the business is generating regular revenue—even when GST data is unavailable.
But this does not mean every business without GST registration will automatically qualify for an SBI loan.
Credit assessment, KYC, repayment capacity, banking history and other eligibility requirements will still matter.
SBI is already using digital data for MSME lending
SBI says its existing digital lending processes can assess eligible GST-registered businesses using GST, PAN and other information.
According to SBI’s official information, its SME Digi Sugam product currently has GST-related eligibility requirements, showing why the proposed UPI-based approach could be significant for businesses outside that system.
SBI has also said it has written around ₹1 lakh crore of loans over the previous 18 months using GST and PAN data.
What small businesses should do now
If you want your digital transaction history to strengthen your future borrowing profile, start treating your business payments like financial records.
Keep these habits:
- Accept customer payments through traceable digital channels.
- Use a dedicated business bank account where practical.
- Keep personal and business transactions separate.
- Maintain proper invoices and sales records.
- Keep PAN and other KYC details updated.
- Consider Udyam registration if eligible.
- Maintain a healthy repayment and banking history.
- Do not assume that UPI transactions replace tax or accounting compliance.
Most importantly, do not take unnecessary cashless transactions or borrow simply to create UPI activity. Lenders ultimately need genuine business cash flow.
If you’re planning to apply for business finance, preparing your numbers and business plan in advance can make the process much easier. See our guide on How to Write a PMEGP Project Report That Gets Approved to understand what lenders typically look for in a practical project report.
Is SBI already offering a “loan without GST”?
Not yet in the sense of a broadly available new SBI product based solely on UPI.
The current announcement is about a solution under development. SBI’s official digital-lending information continues to list specific eligibility requirements for existing products, including GST-related requirements for SME Digi Sugam.
So, if you see advertisements claiming “SBI UPI loan without GST—apply now”, verify the offer directly with SBI before sharing documents, OTPs or banking credentials.
Why this could be a big change for micro businesses
The bigger story is not simply “loan without GST.”
It is the move towards cash-flow-based lending.
A small business may not have a large balance sheet or extensive financial statements, but it may have hundreds of genuine digital customer payments every month.
If lenders can responsibly use consent-based transaction data to understand that cash flow, more micro businesses could potentially enter the formal credit system.
For India’s smallest businesses, that could be a much bigger development than another conventional loan scheme.
Bottom line
The proposed SBI UPI business loan without GST could make formal business credit more accessible to eligible small businesses that have limited traditional financial data but strong digital payment records.
However, the facility is still being developed, and UPI payments alone should not be treated as a guaranteed loan approval or a substitute for GST, accounting or other legal requirements.
For small businesses, the message is simple: build a genuine, transparent digital transaction trail today—it could become increasingly valuable when you need credit tomorrow.
Sources & references
- Business Standard — SBI to use UPI data to lend to small businesses without GST registration
- The Economic Times — SBI developing UPI-data solution for small-business credit assessment
- SBI — Digital Lending Guidelines
- SBI — SME Digi Sugam
Editorial & AI Disclosure: This article is an independently prepared editorial explainer based on publicly available information and official SBI material. AI assistance was used for research organisation and drafting. The article does not constitute financial, tax or legal advice. SBI’s proposed UPI-based lending solution is under development; eligibility, availability, terms and documentation should be confirmed directly with SBI before making any financial decision.