Social Security COLA 2027: Why a Bigger Increase May Still Not Mean More Money
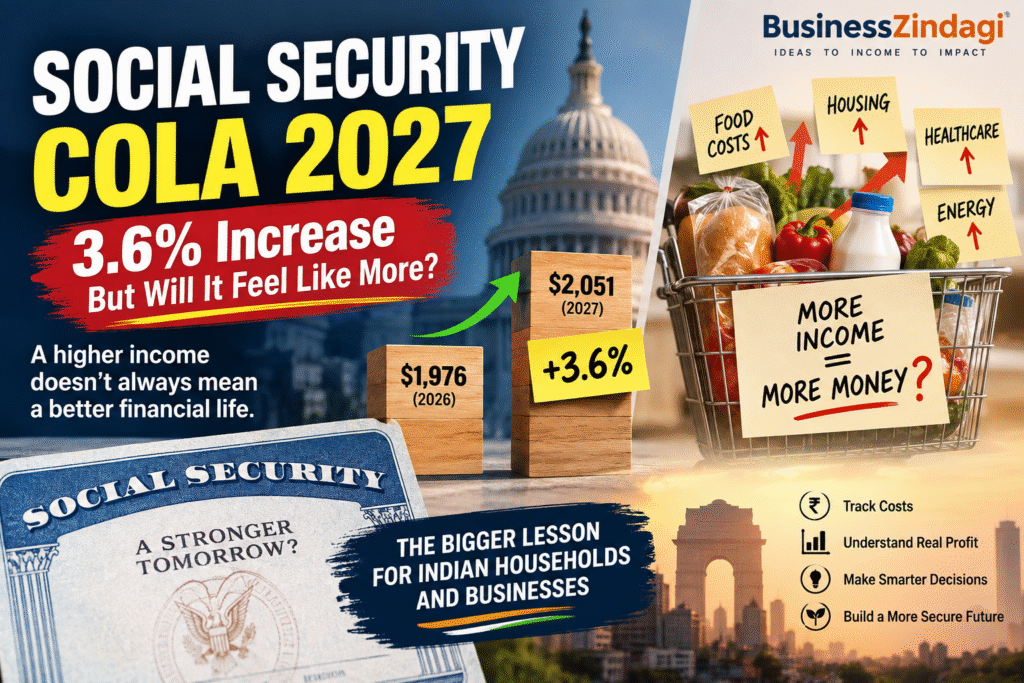
The Social Security COLA 2027 estimate is attracting attention after AARP projected a 3.6% cost-of-living adjustment for Social Security benefits next year.
That could mean roughly $75 more per month for an average retired worker based on current average benefits. But the official 2027 COLA has not yet been announced. It will be calculated using third-quarter inflation data and is expected to be announced on October 14, 2026.
At first glance, a bigger Social Security payment sounds like good news.
But there is a catch.
A higher income does not automatically mean more money left over.
And that is a financial lesson that applies far beyond Social Security or the United States.
What Is the Social Security COLA for 2027?
The Social Security cost-of-living adjustment, or COLA, is an annual increase designed to adjust benefits for inflation.
AARP’s latest estimate puts the 2027 Social Security COLA at 3.6%. The Senior Citizens League has estimated about 3.5%, showing that the final number is still uncertain.
The official figure will depend on inflation data for July, August and September. The September inflation report is scheduled for October 14, when the Social Security Administration is expected to announce the official 2027 COLA.
So for now:
3.6% is an estimate — not the final COLA.
Why Are Some Experts Warning People Not to Get Too Excited?
The problem is simple.
If your income rises but your essential expenses rise almost as quickly, your purchasing power may not improve much.
A COLA is intended to compensate for inflation. It is therefore not necessarily a “real” increase in financial wealth.
For example, if someone’s income rises by 3.6% but the things they regularly buy become 4% more expensive, they have more money in nominal terms but less purchasing power.
This is why some experts and advocates argue that beneficiaries can still feel financially squeezed despite receiving a larger check. Rising costs for food, energy, housing and healthcare can be particularly significant for older Americans.
A Simple Example: More Income, Less Money Left
Consider a hypothetical household earning ₹50,000 per month.
Suppose its income increases by 3.6%.
Old income: ₹50,000
New income: ₹51,800
That looks positive.
But suppose monthly expenses increase from ₹40,000 to ₹42,500.
Before
₹50,000 income
− ₹40,000 expenses
= ₹10,000 left
After
₹51,800 income
− ₹42,500 expenses
= ₹9,300 left
The income increased by ₹1,800.
But the amount actually left over fell by ₹700.
That’s the important distinction between income growth and real financial improvement.
The Bigger Lesson: Don’t Look at Income Alone
This is where the Social Security story becomes relevant to people outside the U.S.
Whether you are:
- a salaried employee,
- a freelancer,
- a pensioner,
- a self-employed professional,
- an MSME owner, or
- an entrepreneur,
your income alone does not tell you whether your financial position is improving.
You should also track:
Income → Expenses → Debt/EMIs → Money left over
That final number is often much more important than the headline increase in income.
The Same Problem Happens in Indian Businesses
A similar mistake happens in business.
Imagine a small business increases monthly sales from ₹10 lakh to ₹11 lakh.
It is tempting to celebrate a 10% increase.
But now suppose costs increase from ₹8 lakh to ₹9.5 lakh.
Before
₹10 lakh sales
− ₹8 lakh costs
= ₹2 lakh surplus
After
₹11 lakh sales
− ₹9.5 lakh costs
= ₹1.5 lakh surplus
Sales increased by 10%.
But the amount left after costs fell by 25%.
This is why business owners should never judge business performance from revenue alone.
Revenue is not profit.
And higher sales do not automatically mean better financial performance.
Income Up Doesn’t Always Mean Financial Health Up
There are several numbers that are easy to confuse:
Income
Money coming in.
Revenue
Business sales before costs.
Profit
What remains after applicable business expenses.
Cash flow
When money actually enters and leaves.
Surplus
Money remaining after the expenses and commitments you are measuring.
These numbers answer different questions.
A person or business can have:
Higher income + higher expenses = little improvement
or even:
Higher revenue + much higher costs = lower profit
What Should You Actually Track?
A simple monthly financial check can focus on five numbers.
1. Total income
How much money actually came in?
2. Essential expenses
How much was required to maintain your household or business?
3. Debt and fixed commitments
How much income is already committed to EMIs, rent and other obligations?
4. Money left over
What remains after the major costs?
5. Change in your surplus
Is the amount you actually keep increasing or decreasing?
This last number can tell you more about your financial health than an income increase alone.
What Does the Social Security Story Mean for Indian Readers?
The 2027 COLA is a U.S. policy issue. It does not directly change salaries, pensions or Social Security benefits in India.
But the underlying financial lesson is universal.
Inflation can quietly consume an income increase.
For an employee, a salary hike may be partly absorbed by higher living costs.
For a pensioner, a benefit increase may not fully compensate for the costs that matter most to their household.
For an entrepreneur, higher sales may be absorbed by higher raw-material, labour, rent, financing or logistics costs.
So instead of asking only:
“How much did my income increase?”
ask:
“How much more money do I actually have left after my costs?”
For Small Businesses, Profit Matters More Than the Headline Sales Number
A business owner should regularly compare:
Revenue growth
against
Cost growth
and ultimately:
Profit growth
For example:
| Metric | Earlier | Now |
|---|---|---|
| Sales | ₹10 lakh | ₹11 lakh |
| Costs | ₹8 lakh | ₹9.5 lakh |
| Money left | ₹2 lakh | ₹1.5 lakh |
The business is selling more.
But financially, it is keeping less.
That is why cost tracking and profit analysis are just as important as sales growth.
The BusinessZindagi Takeaway
The Social Security COLA debate provides a useful reminder:
A bigger number does not always mean a better financial position.
A salary can increase.
A pension can increase.
Sales can increase.
Revenue can increase.
But if costs rise faster, the money actually available to you may not improve.
For individuals, that means paying attention to purchasing power and monthly surplus.
For businesses, it means paying attention to costs, margins, cash flow and profit.
The real question is not:
“How much more did I earn?”
It is:
“How much more did I actually keep?”
What Happens Next With the 2027 Social Security COLA?
The current 3.6% estimate is not final.
The Social Security Administration’s official calculation uses inflation data from the third quarter, and the September CPI data is due on October 14. The official 2027 COLA is expected to be announced that day.
That means the current estimate could still change before the official announcement.
BusinessZindagi will update this article when the official figure is released.
Frequently Asked Questions
What is the Social Security COLA for 2027?
The latest AARP estimate is 3.6%, while other estimates are around 3.5%. The official 2027 COLA has not yet been announced.
When will the 2027 Social Security COLA be announced?
The official COLA is expected to be announced on October 14, 2026, following the release of September inflation data.
How much could the average Social Security check increase?
A 3.6% COLA would translate to roughly $75 more per month for an average retired worker based on current average benefits. The actual increase for an individual depends on their benefit amount.
Does a higher COLA mean retirees will have more purchasing power?
Not necessarily. A higher COLA is designed to reflect inflation. If the costs of goods and services rise at a similar or faster rate, the real improvement in purchasing power can be limited.
Does the Social Security COLA affect India?
No. The U.S. Social Security COLA does not directly change Indian salaries, pensions or benefits. However, the underlying lesson about income, inflation and purchasing power is relevant to Indian households and businesses.
Authentic Sources & References
- AARP — 2027 Social Security COLA Estimate — Current estimate and explanation of how the 2027 COLA is being calculated.
- CBS News — 2027 Social Security COLA Projection — Reports the latest 3.6% AARP projection and the expected October 14 announcement.
- Social Security Administration — Cost-of-Living Adjustments — Official U.S. Social Security information and COLA updates.
- U.S. Bureau of Labor Statistics — Consumer Price Index — Official inflation data used in the COLA calculation.
Relevant BusinessZindagi Resources
I would add these inside the article, rather than putting a large list at the bottom:
- Cost/profit tracking: BusinessZindagi CostTrack — Useful for tracking business costs and understanding how expenses affect the actual financial result.
- Cash-flow tracking: BusinessZindagi AI CashBook — Useful for tracking everyday business income and expenses.